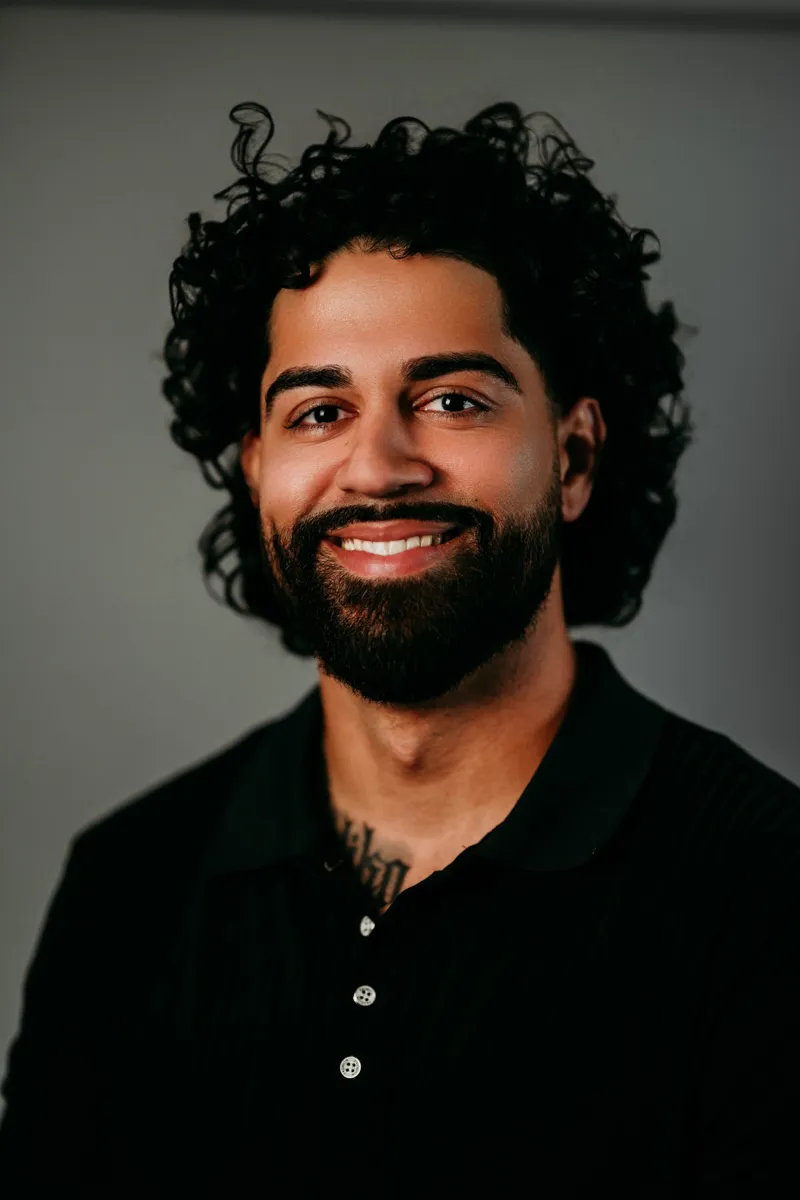
Cristian Gonzalez
Cristian GonzalezeXp Realty · Ocala, FL · Lic #3633800
Ocala · Marion County · 2026 Edition

The Ocala Buyer's Guide

How to buy a home in Ocala and Marion County with a plan, real numbers, and no surprises.

For first-time buyers, Veterans, and anyone moving to Ocala.

Read it online
Cristian Gonzalez, Ocala REALTOR and U.S. Navy Veteran
Cristian GonzalezREALTOR® · eXp Realty · U.S. Navy Veteran
Born and raised in Marion County
Free PDF · 14 pages

Get the printable guide

Checklists, a showing scorecard, contract date tracker, and the full Florida glossary. It downloads instantly and a copy goes to your inbox.

No spam. By submitting, you agree Cristian Gonzalez may contact you about your home search. Reply STOP to texts any time.

The process

8 steps to buying a home in Florida

Florida contracts run on hard deadlines. Here's the order things happen, and roughly when.

  1. 1

    Strategy call

    30 minutes

    We talk goals, budget, areas, and timeline. Before touring, we sign a written buyer agreement. It spells out what I do for you and how I'm paid. Compensation is negotiable and we decide it together.

  2. 2

    Get pre-approved

    Before you tour

    Not just pre-qualified. A lender verifies income, assets, and credit. Ask for a payment estimate that includes taxes, insurance, and HOA so you shop by monthly cost, not just price.

  3. 3

    Tour homes

    1 to 4 weeks, typically

    In person or by live video. I'll flag the Florida issues that matter early: roof age, insurability, flood zone, well and septic, HOA or CDD fees.

  4. 4

    Write the offer

    Same day you decide

    Most offers here use the Florida Realtors/Florida Bar contract, often the "AS IS" version. We set price, escrow deposit, inspection period, financing terms, closing date, and any seller contributions.

  5. 5

    Escrow deposit

    Usually within 3 days

    Once the contract is effective, your deposit goes to the title company or escrow agent, usually within 3 days. It's credited back to you at closing. Always confirm wiring instructions by phone.

  6. 6

    Inspection period

    Commonly 10 to 15 days

    General inspection, termite (WDO), 4-point and wind mitigation, plus septic and well if needed. Get insurance quotes now, not later. This is your window to negotiate or walk away.

  7. 7

    Appraisal, loan, and title

    Weeks 2 to 4

    The lender orders the appraisal and finishes underwriting. The title company searches for liens and prepares title insurance. You bind homeowners insurance.

  8. 8

    Walkthrough and closing

    Closing day

    We do a final walkthrough, then you sign with the title company in person or remotely. Funds are disbursed, the deed is recorded, and you get the keys.

Timeline: Most financed purchases in Marion County close in about 30 to 45 days from contract. Cash can be faster.
What out-of-state guides miss

Florida buyer realities

These change your payment, your timeline, or your risk. Most get decided during the inspection period. More detail: homestead exemption guide.

Insurance drives your payment

Get quotes during your inspection period, not after. Insurers look hard at roof age, roof type, electrical, plumbing, and A/C. Older homes usually need a 4-point inspection. A wind mitigation report can lower your premium. Citizens Property Insurance is Florida's state-backed insurer of last resort.

Flood zones exist inland

Marion County is inland, but low areas still sit in flood zones. If a home is in a high-risk zone (A or AE) and you use a federally backed loan, flood insurance is required. Check the FEMA map and the seller's disclosure for past water issues.

Sinkhole coverage is separate

Marion County sits on limestone and is a sinkhole-prone area. Standard Florida policies cover catastrophic ground cover collapse. Broader sinkhole coverage is usually optional and priced separately. Ask about past claims on the home.

Your taxes will not match the seller's

The seller's bill may reflect years of homestead savings. After you buy, the home is reassessed. Budget from the purchase price, not the current tax bill. Your lender can estimate it.

Homestead saves you money every year

If the home is your permanent residence on January 1, apply with the Marion County Property Appraiser by March 1. It can reduce assessed value by up to $50,000 and caps future assessed value increases under Save Our Homes.

Well and septic are common

Many homes in Marion Oaks, Silver Springs Shores, and rural areas use septic, and some use private wells. Budget for a septic inspection and a water test. FHA and VA lenders often require a well water test.

Read the HOA, CDD, and deed restrictions

A CDD (Community Development District) assessment shows up on your tax bill. HOA and deed rules can limit RVs, boats, fences, sheds, and rentals. Read them before your inspection period ends.

Wire fraud is real

Criminals send fake wiring instructions that look like they're from the title company. Never wire money based on an email alone. Call the title company at a number you found yourself and confirm before you send anything.

Money

What to budget for

Know where every dollar goes before you write an offer. Your lender's Loan Estimate turns these into your exact numbers. See the Florida closing costs guide or run your payment in the mortgage calculator.

Escrow deposit

Paid at contract, credited back to you at closing. Amount is negotiable and set in the offer.

Inspections

General, WDO (termite), 4-point, wind mitigation, plus septic and well testing if needed. Paid upfront to inspectors.

Appraisal

Ordered by your lender. Often paid upfront or at closing.

Down payment

From 0% (VA, USDA) to 3% to 3.5% (conventional, FHA) and up, depending on the loan.

Closing costs

Lender fees, title charges, prepaid insurance and taxes, and escrow reserves. Often 2% to 5% of the price. Your Loan Estimate shows your real numbers.

Florida loan taxes

With a mortgage, buyers usually pay state documentary stamp tax on the note (35 cents per $100) and intangible tax (0.2% of the loan amount).

Sellers can contribute toward your closing costs if it's negotiated in the contract. Who pays for the owner's title policy is also set in the contract. In Marion County the seller often pays it, but it's negotiable.
Veteran to Veteran

Buying with a VA loan

I served in the Navy as an IT. I know what this benefit is worth, and I've seen VA offers treated like weaker offers. They aren't, when they're written right.

$0 down

Eligible Veterans with full entitlement can buy with no down payment and no VA loan limit.

No monthly mortgage insurance

Unlike FHA and most low-down conventional loans.

Funding fee

A one-time fee that can be financed. It's waived for Veterans receiving VA disability compensation.

Seller concessions

VA allows seller concessions up to 4% of the home's value, on top of normal closing costs a seller pays.

VA appraisal

Checks Minimum Property Requirements: safe, sound, and sanitary. Older homes may need repairs before closing.

Certificate of Eligibility

Your lender can usually pull your COE online. Have your DD-214 ready.

How I make your VA offer stronger

  • Pre-approval from a lender who closes VA loans regularly
  • Clean terms and a real escrow deposit to show commitment
  • I walk the listing agent through the VA appraisal upfront so there are no surprises
  • We screen homes for roof, water, and electrical issues that can stall a VA appraisal

Florida tax exemptions for Veterans

Florida also offers property tax exemptions for eligible Veterans, including an extra $5,000 exemption with a service-connected disability of 10% or more, and a full homestead exemption for 100% permanent and total disability. Confirm eligibility with the Marion County Property Appraiser.

Read the full VA home buying guide →

First-time buyers

Buying your first home

FHA

As little as 3.5% down with a 580+ credit score. Flexible on credit.

Conventional

As little as 3% down for qualifying first-time buyers. Mortgage insurance can be removed later.

VA

0% down for eligible Veterans and service members.

USDA

0% down in eligible rural areas. Parts of Marion County may qualify. Check the USDA map.

Down payment help is worth asking about: Florida Housing Finance Corporation programs and Marion County's SHIP purchase assistance for income-eligible buyers. Funding and rules change often, so your lender confirms what's open now.

More for first-time buyers →

Until closing, don't:

  • Open new credit cards or finance a car
  • Change jobs without telling your lender
  • Move large sums of money without a paper trail
  • Co-sign for anyone
  • Miss a document request from your lender
Moving to Ocala

Relocating from out of state

Want the full picture? Get the Ocala relocation guide for your region.

Buy from anywhere

Live video tours, e-signing, and remote online notarization mean you can close without flying in.

Know the map

I-75 runs north and south through Ocala. Gainesville is about 45 minutes north. Orlando and Tampa are each roughly 1.5 hours.

Compare the full cost

Florida has no state income tax, but insurance and taxes matter more here. Get real quotes before comparing.

New-resident deadlines

Florida generally expects a Florida driver license within 30 days of becoming a resident. Check FLHSMV for vehicle registration rules.

Plan homestead

Own and live in the home on January 1, apply by March 1. Timing your closing matters.

Make one visit count

If you can visit once, we can tour across two or three areas in a day so you leave with a clear favorite.

Where to look

Ocala area guide

Five areas my buyers ask about most. Every street is different, so use this as a starting point, then we narrow it down together.

SW Ocala

34476

South and west of I-75 along the SR 200 corridor. A mix of established subdivisions, 55+ and gated communities, and newer construction, close to SR 200 shopping, dining, and medical offices with quick I-75 access.

What to checkHOA rules and fees vary a lot by community. Age-restricted communities have their own residency rules.Explore SW Ocala →

Marion Oaks

34473

One of the largest planned communities in Marion County, southwest of Ocala near I-75 at CR 484. Mostly newer single-family homes, active new construction from national builders, larger lots, and some of the most affordable prices in the county. Most sections have no HOA.

What to checkSeptic on most homes, builder contract terms, and what can be built on vacant lots next door. The community is large, so check drive times.Explore Marion Oaks →

West Ocala

34481

West of I-75 along the SR 200 corridor toward Dunnellon. Established neighborhoods, larger lots, pockets of acreage, and several master-planned communities, including On Top of the World.

What to checkWell and septic on acreage, deed restrictions on animals and outbuildings, and drive times to work and shopping.Explore West Ocala →

On Top of the World

55+ community

A large 55+ active adult community off SR 200 with golf, fitness, pools, pickleball, clubs, and a town center at Circle Square. Resale homes plus newer construction in later phases.

What to checkMonthly fees and exactly what they cover, age and occupancy rules, and the community documents before your inspection period ends.Explore On Top of the World →

Silver Springs Shores

34472

A large, established community southeast of Ocala off SR 464 and Baseline Road. Homes from the 1970s onward plus steady new construction on remaining lots. Many sections have deed restrictions but no mandatory HOA.

What to checkRoof age and insurability on older homes, the 4-point inspection, septic condition, and whether an HOA or deed restrictions apply to that section.Explore Silver Springs Shores →

Area descriptions are general and not a guarantee of any property's features, fees, or restrictions. Confirm details for each home.

Checklists

Stay ahead of every deadline

The PDF version has these as printable checklists, plus a showing scorecard and a contract date tracker. Get the PDF.

Pre-approval documents

  • Government-issued photo ID
  • Pay stubs covering the last 30 days
  • W-2s for the last 2 years
  • Federal tax returns for the last 2 years (self-employed: business returns and a year-to-date P&L)
  • Bank statements for the last 2 months, all pages
  • Retirement and investment account statements
  • A short letter explaining any large deposits
  • Gift letter, if family is helping with funds
  • Veterans: DD-214 or Statement of Service
  • Divorce decree or support orders, if they apply

Once you're under contract

  • Send the escrow deposit by the deadline (confirm wiring by phone)
  • Schedule inspections in the first few days
  • Get homeowners (and flood, if needed) insurance quotes
  • Send lender documents the same day they're requested
  • Read HOA, CDD, and deed restriction documents
  • Decide on repairs or credits before the inspection period ends
  • Talk with your lender about locking your rate
  • Review your Closing Disclosure (you get it at least 3 business days before closing)
  • Set up utilities, internet, and trash service
  • Final walkthrough before signing

Closing day

  • Photo ID for everyone signing
  • Closing funds sent by verified wire or cashier's check, per title instructions
  • Homeowners insurance bound and sent to your lender
  • Questions about your Closing Disclosure answered beforehand
  • Collect keys, remotes, gate cards, and codes
  • Change the locks and garage codes
  • Calendar reminder: file homestead by March 1
Plain English

Real estate terms, Florida edition

The words you'll hear from your lender, title company, and inspector, explained simply.

"AS IS" contract
The Florida Realtors/Florida Bar "AS IS" Residential Contract. The seller isn't required to make repairs, but you can cancel for any reason during the inspection period.
Appraisal
An independent opinion of value ordered by your lender to confirm the home supports the loan amount.
Buyer agreement
A written agreement you sign before touring. It explains my services, the term, and how I'm paid. Compensation is negotiable.
CDD
Community Development District. A special district that funds infrastructure in some communities, billed through your property taxes.
Certificate of Eligibility (COE)
The VA document that confirms your VA loan entitlement.
Closing
The appointment where documents are signed, funds are disbursed, and the deed is recorded. In Florida it's usually handled by a title company.
Closing costs
Fees beyond the price and down payment: lender fees, title charges, prepaid taxes and insurance, and government recording fees and taxes.
Closing Disclosure
The final statement of your loan terms and costs. You receive it at least 3 business days before closing.
Comparables (comps)
Recently sold, similar homes nearby that are used to judge value.
Debt-to-income (DTI)
Your monthly debt payments divided by gross monthly income. Lenders use it to set what you can borrow.
Documentary stamp tax
Florida's tax on deeds and mortgage notes. Sellers customarily pay it on the deed. Buyers with a loan pay it on the note.
Effective Date
The date the contract is fully signed and delivered. Your deadlines count from this date.
Equity
The difference between what your home is worth and what you owe on it.
Escrow deposit
Florida's term for earnest money. Held by a title company or escrow agent and credited to you at closing.
FHA loan
A loan insured by the Federal Housing Administration, with as little as 3.5% down.
Fixed rate vs. ARM
A fixed rate never changes. An adjustable-rate mortgage (ARM) is fixed for a set period, then adjusts.
4-point inspection
An insurance inspection of roof, electrical, plumbing, and HVAC. Common for older homes.
Homestead exemption
A Florida property tax exemption for your permanent residence. Apply by March 1.
Home warranty
An optional one-year service plan that covers repair or replacement of certain systems and appliances.
Inspection period
The set number of days after the Effective Date to inspect, get quotes, negotiate, or cancel.
Loan Estimate
A standard three-page form from your lender that shows your estimated rate, payment, and closing costs.
MLS
The Multiple Listing Service. A regional database of homes for sale shared among cooperating brokers.
Mortgage insurance
Insurance that protects the lender on low-down-payment loans. Called PMI on conventional loans and MIP on FHA loans.
PITI
Principal, interest, taxes, and insurance: the four parts of a typical monthly mortgage payment.
Pre-qualification
A quick estimate based on what you tell a lender. Nothing is verified yet.
Pre-approval
The lender has verified your income, assets, and credit. This is what sellers want to see with an offer.
REO
Real estate owned. A home a bank took back through foreclosure and is now selling.
Short sale
A sale where the seller's lender agrees to accept less than what's owed.
Survey
A drawing of the property's boundaries, improvements, and any encroachments.
Title insurance
Protects against problems with ownership history. Lenders require a lender's policy. An owner's policy protects you.
Transaction broker
Florida's default relationship. The licensee gives limited representation to a buyer or seller. Ask me how it applies to you.
Underwriting
The lender's final review of you and the property before approving the loan.
USDA loan
A zero-down loan for eligible buyers in qualifying rural areas.
VA loan
A loan guaranteed by the Department of Veterans Affairs for eligible Veterans, service members, and some surviving spouses.
Wind mitigation
An inspection that documents features like roof straps and shutters. It can lower your insurance premium.
In their words

What clients say

Real reviews from my Google Business Profile. See more reviews.

★★★★★
“Cristian Gonzalez helped me buy my home in Marion Oaks and made the whole process simple. He knew the Ocala market, answered every question fast, and stayed on top of every deadline so nothing fell through the cracks. He was honest with me about what each home was actually worth instead of just trying to get me to the closing table.”
Tashana S. · Buyer, Marion Oaks
★★★★★
“Cristian did an excellent job helping us sell our home in Southwest Ocala for $325,000 and purchase our new home in Southeast Ocala for $265,000. There were a few unexpected challenges during the process, but he stayed on top of everything, communicated clearly, and always had a plan for moving us forward.”
Juan F. · Seller and buyer, Ocala
★★★★★
“He was professional, knowledgeable, responsive, and truly cared about helping us find the right home. He made the entire process smooth and stress-free. We highly recommend Cristian to anyone looking for a great realtor!”
Khaleim S. · Buyer
★★★★★
“He guided our family through both selling our home and finding the perfect new one for our next chapter. The journey wasn't always easy, but Cristian was patient, encouraging, and available whenever we had questions or concerns.”
Geisha · Seller and buyer
★★★★★
“His professionalism, knowledge, responsiveness, and genuine dedication made the entire process feel smooth and stress-free. We truly appreciated having someone we could trust every step of the way.”
Betty C. · Buyer
★★★★★
“Cristian runs a true system, not just a listing. From pricing to marketing to negotiations, everything was intentional and well thought out. He protected our leverage, kept us informed, and stayed ahead of issues before they became problems.”
King L. · Seller
Quick answers

Ocala home buying FAQ

How long does it take to buy a home in Ocala?

Most financed purchases in Marion County close in about 30 to 45 days from an accepted contract. Cash purchases can close faster. Add time before that for pre-approval and touring.

How much is the escrow deposit in Florida?

There's no fixed amount. It's negotiated in the offer and is usually due to the title company or escrow agent within 3 days of the contract's Effective Date. It's credited back to you at closing.

Do I need a 4-point inspection in Ocala?

Many insurers require a 4-point inspection on older homes. It covers the roof, electrical, plumbing, and HVAC. A wind mitigation inspection is separate and can lower your premium.

When do I file for homestead exemption in Marion County?

If the home is your permanent residence on January 1, apply with the Marion County Property Appraiser by March 1 of that year.

Can I use a VA loan to buy in Ocala?

Yes. Eligible Veterans with full entitlement can buy with no down payment and no monthly mortgage insurance. The home must meet VA Minimum Property Requirements at appraisal.

Do I have to sign a buyer agreement before touring homes?

Yes. Agents now need a written agreement with you before touring. It explains the agent's services and compensation, and compensation is negotiable.

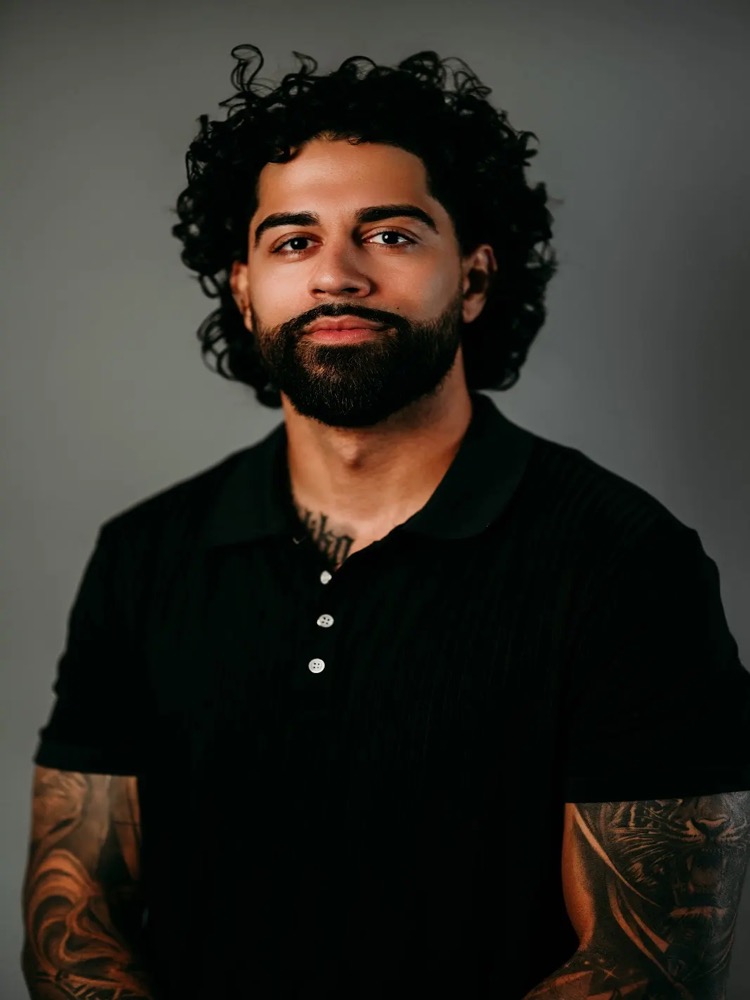
Cristian Gonzalez, REALTOR with eXp Realty in Ocala, Florida
Meet your agent

Cristian Gonzalez

I was born and raised in Marion County, served in the U.S. Navy as an Information Systems Technician (IT), and now help people buy homes in the place I grew up.

I'm a REALTOR® with eXp Realty and a member of the Ocala/Marion County Association of REALTORS® (OMCAR). I treat your purchase like the financial decision it is: real numbers before you fall in love with a house, protected deadlines once you're under contract, and straight answers about what a home is actually worth.

That's what my tagline means. I don't just find homes, I engineer your wealth. The right home at the right terms is the start of your equity, not just a place to live.

U.S. NavyVeteran
Marion CountyBorn and raised
8 homesClosed in 2026
OMCARMember board

Numbers first

We start with your true monthly cost: principal, interest, taxes, insurance, and any HOA or CDD.

Deadlines are protected

Florida contracts run on hard dates. I track every one so your deposit stays safe.

Straight answers

If a house is overpriced or has an insurance problem, you hear it from me first.

Buyer representation

From the first call to the keys, including offer strategy, negotiation, and deadline management.

VA buyers

Veteran to Veteran. I know how to write a VA offer that sellers take seriously.

First-time buyers

Plain-English guidance, loan options, and down payment assistance worth asking about.

Relocation

Live video tours, remote signing, and an honest read on areas before you ever visit.

New construction

The builder's rep works for the builder. I work for you on contracts, upgrades, and incentives.

Your next step

Let's build your buying plan.

A 30-minute strategy call. No pressure, no obligation. You'll leave with your real monthly payment, the areas that fit, and a timeline that works.

Call or textGet the PDF